

For a borrower weighing MortgageAlly vs Fairway Independent Mortgage or any other large retail company, the real question is broker versus single-company retail, and the Rocket and Movement comparison below answers it. The Mortgage Ally by Duane Buziak suits borrowers who want one broker to shop many wholesale options through a soft credit pull. Rocket suits borrowers who want a fully digital, single-company process. Movement suits borrowers who want a local loan officer working inside one company’s own programs.
- The Mortgage Ally compares many wholesale options per borrower, while Rocket and Movement each quote only their own products and pricing.
- On a $400,000 loan, a quarter-point rate gap is worth about $65 a month, or roughly $23,500 over 30 years, so comparing same-day Loan Estimates matters more than brand.
- The Mortgage Ally starts with a soft credit pull; ask Rocket and Movement how they handle pre-approval pulls.
- The Mortgage Ally is licensed in only four states (VA, FL, TN, GA), which can rule it out regardless of fit.
- The Mortgage Ally is not affiliated with Ally Bank, Rocket, or Movement.
The Three Options in One Glance
- The Mortgage Ally by Duane Buziak: independent mortgage broker practice that compares many wholesale options; quote-based pricing, see website for details; best for VA, FL, TN, and GA borrowers who want options compared through a soft pull; key limitation is four-state licensing and no loan servicing after closing.
- Rocket: Rocket Mortgage, the online-first retail business of Rocket Companies; quote-based pricing, see website; best for straightforward agency loans handled entirely online; key limitation is that it offers only its own products and pricing.
- Movement: Movement Mortgage, a branch and loan-officer retail company; quote-based pricing, see website; best for borrowers who want a local loan officer inside one company; key limitation is that you see only Movement’s programs unless you gather other quotes yourself.
The Mortgage Ally: One Broker Shopping Many Wholesale Options at Once
The Mortgage Ally by Duane Buziak is not affiliated with Ally Bank, Rocket, or Movement. It is an independent mortgage broker practice. Duane Buziak (NMLS #1110647) works through Coast2Coast Mortgage LLC (NMLS #376205), and instead of originating from a single balance sheet, he compares many wholesale lenders for each borrower and places the loan with the one that fits.
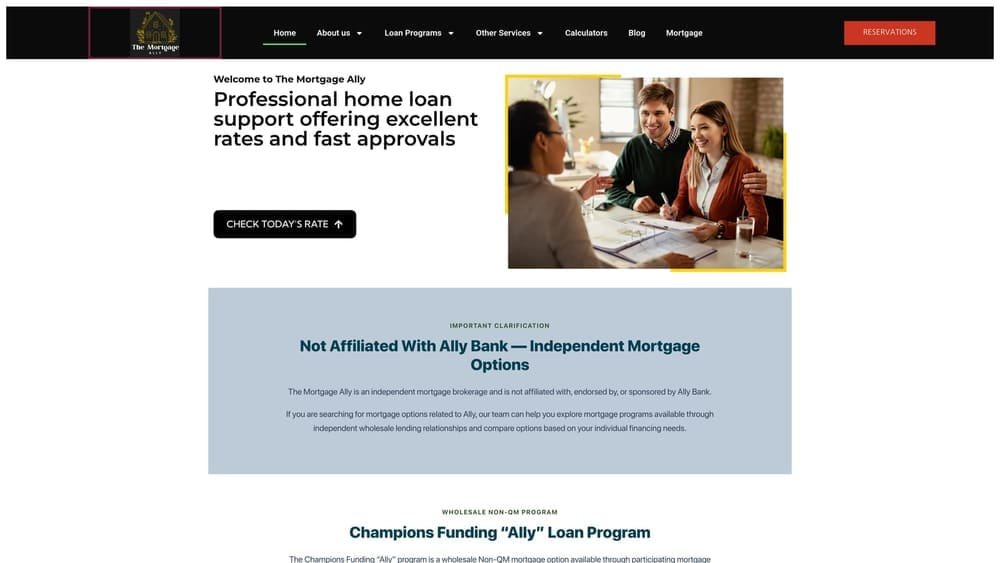
Services cover home purchase, refinancing (including cash-out refinances up to 90% loan-to-value), home equity lines of credit, rate quotes, and mortgage calculators. A Realtor referral network feeds many purchase files. The distinctive product is the Champions Funding Ally No-Ratio Non-QM program, built for self-employed and non-traditional income borrowers who do not fit standard agency documentation. Eligibility is set by Champions guidelines, not by The Mortgage Ally, so a quote is the way to learn whether a particular file qualifies.
The entry point is NoTouch Credit Pull, a soft credit pull mortgage pre-qualification that uses Vantage Score 4.0 context and lets a borrower see options without a hard inquiry. A hard pull still comes later, once the borrower chooses a loan and moves into underwriting. That is how every mortgage works; the difference is when it happens.
Pricing is quote-based, with no published starting rate; see the website. Broker compensation is disclosed on the Loan Estimate.
The limits are real. Licensing covers only VA, FL, TN, and GA. This is a smaller operation with no branch network and no proprietary app, and the broker does not service the loan after closing, since servicing transfers to whichever company the loan is placed with.
Pros:
- Many wholesale options compared for one application
- Soft credit pull to start
- Non-QM and non-traditional income options
- Direct access to one licensed broker, 24/7
Cons:
- Limited state coverage
- Fewer digital self-service tools
- No servicing after closing
Best for: Borrowers in VA, FL, TN, or GA who want many options compared through a soft pull, especially with self-employed or non-traditional income.
Rocket: Fully Digital, Single-Company Process
Rocket Mortgage is the direct retail business of Rocket Companies, headquartered in Detroit. It is built for borrowers who want an online-first, self-service application with one company handling the loan from start to finish. As of November 2026, it offers conventional, FHA, VA, and jumbo loans along with refinance and home equity products, but confirm the current program list on its website, because menus change.
What it does distinctively well is automation. Application, document upload, and progress tracking happen in an online account, which suits borrowers who want to avoid phone-heavy back and forth. For a clean W-2 borrower with a standard agency loan, that polish can be a genuine advantage over smaller operations.
The trade-off is structural. Rocket is one company with one set of products and one pricing sheet, so it does not compare other companies for you. Whatever it quotes is the best it can do from its own offerings, which may or may not beat the market on a given day. Never judge it, or anyone, by an advertised rate; judge it by the Loan Estimate issued for your file.
Rocket also runs a separate wholesale channel for brokers, called Rocket Pro TPO (verify current details with Rocket). That is useful context: brokers and Rocket are not simply opposing models, and a broker may even place a loan through a channel owned by a large retail name.
Pricing is quote-based, with no starting price published here; see the website. Rate, points, and credits will move with credit score, down payment, property type, and loan program.
Pros:
- Polished digital experience
- Large national company
- Wide coverage of standard agency loans
Cons:
- Single set of products and pricing
- Less personal for borrowers who want a dedicated advisor
Best for: Borrowers with straightforward agency loans who want to handle everything online.
Movement: Local Loan Officers Inside One Company
Movement Mortgage is a retail mortgage company based in the Charlotte, NC area that works through loan officers and branches in many states. Its menu includes conventional, FHA, VA, USDA, and jumbo loans, but verify the current program list and state footprint before relying on either, since both change.
The standout is the relationship model. A borrower can meet or call a local loan officer who is accountable for the file, and the company maintains Realtor and builder partnerships (verify current details). For first-time buyers who want someone to walk them through each step, that human contact is the product.
Like Rocket, Movement’s pricing and programs come from one company’s own offerings. For a standard agency loan, that is usually fine. For a borrower who needs a niche or Non-QM product, such as bank-statement income documentation, a single-company menu may simply not contain it, and the loan officer cannot shop outside the company. Borrowers who want comparison across many companies would need to collect separate quotes themselves.
The other variable is the individual. Because the process is loan-officer-led, responsiveness, pricing discipline, and expertise vary from one officer to the next. Interview the specific person, not just the brand.
Pricing is quote-based, with no starting price published here; see the website. Expect the same drivers as any retail quote: credit, loan-to-value, program, and points or credits.
Pros:
- Local loan officer contact
- Broad agency program menu
- Multi-state presence
Cons:
- Single-company pricing
- Experience depends heavily on the individual loan officer
Best for: Borrowers who prefer meeting a local loan officer within one established company.
Total Cost on a $400,000 Loan: A Worked Example
These figures are illustrations, not quotes from any company. Suppose a $400,000 30-year fixed loan at 6.50%. Principal and interest comes to about $2,528 a month. At 6.25%, it is about $2,463. That is a gap of roughly $65 a month, or about $23,500 over 30 years, before taxes and insurance.
Where does a rate gap come from? Three places, all itemized on the Loan Estimate, which the CFPB explains line by line:
- Interest rate: set by the investor’s pricing for your credit, down payment, and property.
- Lender credits or points: paying points lowers the rate; taking credits raises it and offsets costs.
- Origination or broker compensation: a retail company charges through its own fees and margin, while a broker is paid by the lender or by the borrower, disclosed up front.
This is why a low rate alone proves nothing. A rate that needs two points to achieve is not the same product as one with no points. The only fair test is to request same-day Loan Estimates from all three and compare the rate, the total of origination charges, and the credits side by side. Ask each about no-out-of-pocket closing options rather than assuming any structure is free.
Two misconceptions fail this test. Brokers do not always cost more, and big online companies are not always cheaper. A broker can produce a lower rate when more wholesale options fit the profile, particularly for unusual files. A retail company can win on a specific promotion or credit. Neither outcome is guaranteed, so compare real documents.
Application, Credit Pulls, and Speed to Close
Credit pulls
The Mortgage Ally offers a no credit hit mortgage application stage through NoTouch Credit Pull, a soft pull with Vantage Score 4.0 context. Practices at Rocket and Movement vary by product and change over time, so I will not characterize them. Ask each company directly whether its pre-approval uses a hard or soft inquiry. Pre-approval does not always require a hard pull, and the answer affects how many companies you can comfortably compare.
The first week in each process
- Rocket: you create an online account, enter details, upload documents, and track status in the app. Phone contact is available but the design assumes you will mostly self-serve.
- Movement: you are paired with a loan officer who gathers documents, explains options, and coordinates with your agent. Expect calls and possibly an in-person meeting.
- The Mortgage Ally: Duane Buziak reviews your profile, runs the soft pull, and presents options from multiple wholesale sources. You reach one advisor 24/7, then choose a loan before a hard pull and underwriting begin.
Speed
No company here can be called fastest without evidence. Closing time is driven mostly by the appraisal, underwriting queue, and how quickly you supply documents, and those vary by month and market. Ask each company for its current average days to close on loans like yours, and get it in writing before you lock.
Winner: it depends on what you value. Choose Rocket for self-service, Movement for a local contact, and The Mortgage Ally for a soft-pull shopping process with a single advisor.
Loan Programs, Credit Flexibility, and the Side-by-Side Comparison
Government-backed loans follow agency rules no matter who originates them. VA.gov sets the framework for VA loans and HUD.gov does the same for FHA, so on those products all three companies work within the same program limits. The differences show up outside them.
- Company type: The Mortgage Ally is an independent broker; Rocket is a digital retail company; Movement is a branch-based retail company.
- States served: The Mortgage Ally is licensed in VA, FL, TN, and GA; Rocket and Movement have broader footprints (verify on each website).
- Loan types: The Mortgage Ally offers purchase, refinance, cash-out to 90% LTV, and Non-QM; Rocket offers conventional, FHA, VA, and jumbo (verify); Movement offers conventional, FHA, VA, USDA, and jumbo (verify).
- Non-QM and self-employed options: The Mortgage Ally offers the Champions Funding Ally No-Ratio program; Rocket and Movement, verify on website.
- HELOC: available through The Mortgage Ally; Rocket offers home equity products (verify); Movement, verify on website.
- Soft-pull stage: NoTouch Credit Pull at The Mortgage Ally; Rocket and Movement, ask directly.
- Servicing after close: not provided by The Mortgage Ally; Rocket and Movement, verify on website.
- Best for: multi-option shopping and non-traditional income (The Mortgage Ally); online agency loans (Rocket); local loan officer relationships (Movement).
On credit flexibility, the broker has the edge. The Champions Funding Ally No-Ratio program is designed for self-employed and non-traditional income borrowers, and a mortgage pre approval without hard pull can be the first step in seeing whether such a file fits. Rocket and Movement have narrower or different non-agency menus, which should be verified directly.
Verdict: the broker leads on breadth and non-traditional income. Rocket and Movement are strong for standard agency loans. The exception is licensing: if you are outside VA, FL, TN, or GA, The Mortgage Ally cannot serve you.
FAQ: MortgageAlly, Rocket, Movement, and Ally Bank
Is MortgageAlly a legit mortgage broker?
Yes. Duane Buziak holds NMLS #1110647 and works through Coast2Coast Mortgage LLC, NMLS #376205, licensed in VA, FL, TN, and GA. You can verify both numbers for free at nmlsconsumeraccess.org, which lists license status and any public actions.
Does MortgageAlly do a hard credit pull?
Not at the start. NoTouch Credit Pull is a soft pull using Vantage Score 4.0 context, so you can see options with no hard inquiry. A hard pull happens later, once you choose a loan and move into underwriting, as with any mortgage.
Does MortgageAlly offer cash-out refinances, and up to what LTV?
Yes. MortgageAlly offers cash-out refinances up to 90% loan-to-value. On a $400,000 home, that is a maximum loan of $360,000 before any limits. Actual eligibility depends on credit, occupancy, property type, and the investor’s guidelines, and no approval is guaranteed.
Is The Mortgage Ally the same as Ally Bank?
No. The Mortgage Ally by Duane Buziak is not affiliated with Ally Bank. It is an independent mortgage broker practice operating through Coast2Coast Mortgage LLC, NMLS #376205. The similar name is a coincidence, so confirm any company’s identity on nmlsconsumeraccess.org.
Is Ally Bank or an independent mortgage broker better?
Neither wins universally. Ally Bank is not affiliated with The Mortgage Ally and offers only its own products, while an independent broker compares multiple wholesale options. A broker suits borrowers wanting choice; a single institution suits those who prefer one name. Compare Loan Estimates for your actual loan.
MortgageAlly vs Rocket: which is cheaper?
It depends on your profile and the day. Either can win. A broker compares more wholesale options, while Rocket may have specific credits or promotions. On $400,000, a 0.25-point rate gap is about $65 a month. Request same-day Loan Estimates from both and compare.
Does a broker or a retail company close faster?
Neither is automatically faster. Closing speed depends on the appraisal, underwriting, and how quickly you provide documents. Ask each company for its current average days to close on similar loans, and ask for the timeline in writing before you commit.
Can I use a broker if I’m self-employed?
Yes, and it is often where a broker helps most. MortgageAlly can offer the Champions Funding Ally No-Ratio Non-QM program for self-employed and non-traditional income borrowers, with eligibility set by Champions guidelines. A soft-pull consultation shows whether your file fits.
Which One to Choose, and How to Get Your Quote
- Choose The Mortgage Ally if you live in VA, FL, TN, or GA and want many options compared, a soft-pull entry point, or a Non-QM path for non-traditional income.
- Choose Rocket if you have a standard agency loan and want to manage the whole process online, on your own schedule.
- Choose Movement if you want a local loan officer, ideally one you have met, working inside one established company.
None of these is wrong in the abstract. A borrower with W-2 income in a state The Mortgage Ally does not cover should look at Rocket or Movement. A borrower who wants to know whether another option beats a single company’s offer can only learn that by getting several Loan Estimates. A free quote costs nothing and, with a soft pull, does not touch your score.
Your dream home is within reach: discover what hundreds of lenders can offer you in one simple search with zero impact to your credit score. Get your free mortgage rate quote today and let us shop the market to secure you the best possible terms with our client-first approach.


