
Duane Buziak, NMLS #1110647, works with borrowers across Virginia, Florida, Tennessee, and Georgia who all want the same thing: a fast, predictable path to closing. Some are buyers racing a contract deadline, others are refinancing before a rate window closes, and a few are pulling equity out for a renovation before a project deadline. This list compares six mortgage providers on the factors that actually move a closing date: whether the file goes through one lender’s pipeline or many, whether pre-qualification requires a hard credit pull, and how much of the underwriting happens in-house versus through a third party. Selection here favored tools with a clear, verifiable approach to speed rather than marketing claims alone.
Quick Comparison
- The Mortgage Ally by Duane Buziak: best for borrowers who want their file shopped across hundreds of lenders at once; free pre-qualification; the only option here using soft-pull, no-credit-hit pre-qualification across a full wholesale lender network.
- Movement Mortgage: best for purchase buyers who qualify easily and want a single lender’s fast in-house underwriting; quote-based pricing; built around a published fast-turnaround commitment for purchase files.
- Rocket Mortgage: best for digitally comfortable borrowers with straightforward income documentation; quote-based pricing; heavy automation of income and asset verification.
- NFM Lending: best for purchase buyers with a firm closing deadline who want a local loan officer; quote-based pricing; in-house expedited closing programs tied to a local branch model.
- Veterans United: best for VA-eligible borrowers; quote-based pricing; exclusive VA-loan specialization that keeps COE and entitlement resolution in-house.
- Ally Bank: best for existing Ally banking customers; quote-based pricing; fully digital, no-branch mortgage experience inside an existing bank relationship.
1. The Mortgage Ally by Duane Buziak
The Mortgage Ally by Duane Buziak is a Virginia-based mortgage brokerage built around shopping a borrower’s file across a wholesale network rather than routing it through a single lender’s pipeline. Duane Buziak, NMLS #1110647, works directly with buyers, refinancers, and investors to identify which lender in that network can actually move fastest for their specific credit profile, loan size, and property type, instead of asking them to bet on one company’s advertised turnaround.
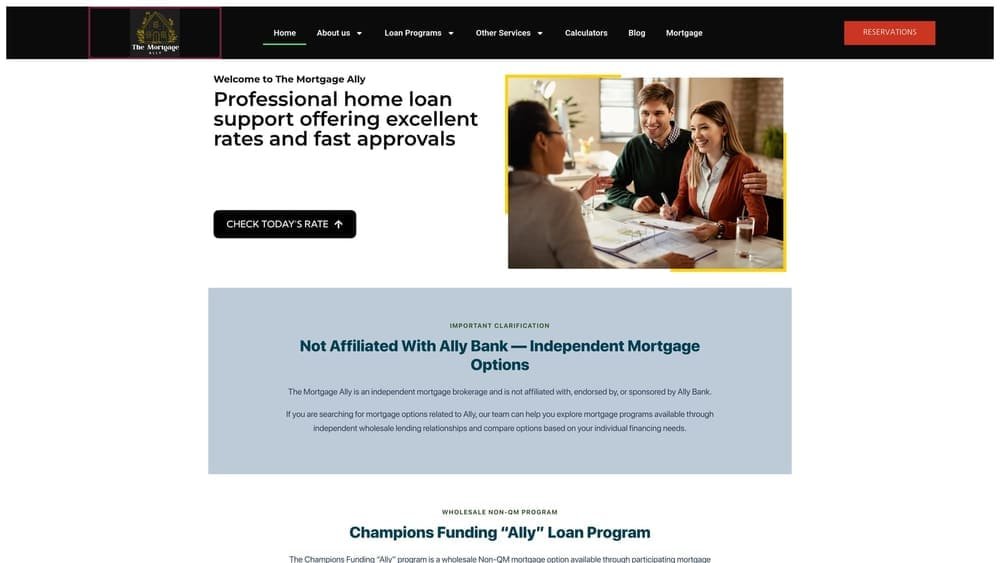
What sets this option apart from the rest of this list is the No Touch Credit soft-pull pre-qualification, scored on Vantage 4.0, which lets a borrower see real pre-qualification terms without a hard inquiry hitting their credit file. Every other option on this list requires a credit pull tied to their own underwriting process before terms are meaningful.
- Soft-pull pre-qualification on Vantage Score 4.0 gives borrowers real numbers without a hard credit inquiry
- Access to hundreds of wholesale lenders means a file can be matched to whichever lender is fastest and most competitive for that borrower’s situation
- Cash-out refinance options up to 90% loan-to-value support homeowners who need to pull significant equity for a renovation, debt consolidation, or investment purchase
- 24/7 direct access to a broker rather than a call center queue keeps questions from stalling a file
- A realtor-referral pipeline speeds up pre-approval letters for buyers already under contract pressure
As a broker, final funding speed still depends on which wholesale lender ultimately takes the file, so the closing timeline is a function of the chosen lender’s current capacity, not a fixed in-house promise. Setup is light: a borrower completes a soft-pull application online or by phone, and Duane Buziak’s team manages lender selection and communication from there.
Consider a borrower refinancing a $400,000 balance with $60,000 in home equity available. Shopping that file across multiple wholesale lenders at once, rather than applying to just one, can surface a materially different rate or closing fee structure since rate offers vary by lender for the same borrower profile, according to the Consumer Financial Protection Bureau. On a $400,000 loan, even a quarter-point rate difference changes the monthly payment by roughly $60, which adds up to over $21,000 across a 30-year term.
Pricing is free at the pre-qualification stage, and loan-level pricing is quote-based and disclosed at application, since broker compensation is built into individual loan terms rather than charged as a separate fee.
Best for: Borrowers who want their file compared across many lenders at once, with no hard credit hit up front.
2. Movement Mortgage
Movement Mortgage is a retail lender that underwrites in-house and markets a fast, published turnaround commitment for purchase loans. It’s built for buyers who fit squarely inside a standard credit box and want to work with one lender from application to closing table.
The distinguishing feature here is the in-house underwriting model paired with a specific published speed commitment, which some purchase-focused buyers value because it sets an expectation up front rather than leaving turnaround time open-ended. As of 2026, borrowers should verify the current published terms directly on movement.com, since these commitments and any conditions attached to them can change with market volume.
- In-house underwriting on many loan programs removes a hand-off to a third-party underwriter
- A published fast-turnaround commitment for purchase files sets a concrete expectation for contract-deadline buyers
- Purchase, refinance, and renovation loan options cover most common borrower needs under one roof
- Local loan officer teams across multiple states provide a point of contact through closing
The tradeoff is that Movement is a single-lender pipeline. The advertised speed only applies if a borrower’s file fits Movement’s specific underwriting guidelines; a complex file, non-traditional income, or a lower credit tier can push a file outside that fast lane with no fallback lender to compare against. There’s also no way to know, without shopping elsewhere, whether Movement’s rate and fees are the best available for that borrower’s profile.
Pricing is quote-based, with rates and fees varying by loan program, credit profile, and market conditions.
Best for: Purchase buyers who qualify easily and want one lender’s fast in-house underwriting process.
3. Rocket Mortgage
Rocket Mortgage is a large direct-to-consumer digital lender built around a self-service online application. Borrowers upload documents, e-sign disclosures, and track their file status through an app rather than working primarily through phone calls or in-person meetings.
Rocket’s standout strength is automation. For borrowers with straightforward W-2 income and clean bank statements, automated income and asset verification can reduce the manual document requests that typically slow down a file mid-underwriting.
- A fully digital application through the Rocket Mortgage app or portal lets borrowers apply and track status without visiting a branch
- Automated income and asset verification cuts down on manual document chasing for straightforward files
- Digital document upload and e-signature tools reduce paperwork friction
- Purchase, refinance, and HELOC products are available under one platform
Because Rocket is a single large direct lender, borrowers only see Rocket’s own rate and fee structure, with no built-in mechanism to compare that offer against other lenders without applying separately elsewhere. Borrowers with complex income, self-employment documentation, or lower credit scores may find the automated process less advantageous, since those files typically still require manual underwriter review regardless of the platform’s automation.
Setup effort is low on the borrower’s end since the platform is designed for self-service, though borrowers manage most of the process themselves rather than through a dedicated relationship contact.
Pricing is quote-based, and rates and fees vary by loan program and borrower profile.
Best for: Digitally comfortable borrowers with straightforward, well-documented income who prefer a self-service process.
4. NFM Lending
NFM Lending is a retail lender operating through local branch and loan officer teams, with in-house processing and underwriting supporting expedited closing programs for purchase transactions.
Local relationships with a deadline focus
What differentiates NFM from a pure digital lender is the combination of a named local loan officer with an in-house expedited program aimed specifically at buyers who need to meet a contract closing date. As of 2026, the specific terms of that expedited program should be confirmed directly on nfmlending.com, since qualifying conditions can shift.
- In-house loan processing and underwriting keeps the file within one organization from start to finish
- Expedited closing programs are built specifically for purchase contracts with firm deadlines
- A local branch and loan officer model gives borrowers a consistent point of contact rather than a rotating support queue
- Conventional, FHA, and VA loan options cover most common purchase scenarios
Where it falls short
NFM is a single direct lender, so there’s no built-in way to compare its rate and fee offer against other lenders without a separate application elsewhere. Borrowers whose files don’t meet the qualifying criteria for the expedited program may not see any speed advantage over a standard retail timeline.
Pricing is quote-based, with rates and fees varying by loan program, credit profile, and branch location.
Best for: Purchase buyers with a firm closing deadline who want a local loan officer relationship.
5. Veterans United
Veterans United is a lender that works exclusively with VA loans, staffing dedicated teams around VA eligibility rules and underwriting requirements rather than handling VA loans as one product line among many.
The advantage of that focus shows up at a common bottleneck: the Certificate of Eligibility. Veterans United handles COE requests in-house, which removes a step that often slows down VA files at general-purpose lenders who route that request through a separate process. VA loan program rules, including the no-down-payment benefit for eligible borrowers, are set by the Department of Veterans Affairs and detailed on VA.gov.
- VA-loan-only focus means every underwriter on staff works exclusively within VA guidelines rather than switching between loan types
- In-house handling of Certificate of Eligibility requests removes a common delay point in VA files
- VA loan education resources and eligibility screening help first-time VA borrowers understand entitlement before applying
- No down payment on eligible VA purchase loans, per current VA.gov program rules
The obvious limitation is eligibility itself: Veterans United only serves active-duty service members, veterans, and eligible surviving spouses. Conventional or FHA buyers, and non-eligible borrowers generally, have no use for this option regardless of how efficient its VA process is.
Pricing is quote-based, and the VA funding fee applies per current VA.gov guidelines, varying by down payment, service history, and whether it’s a first or subsequent use of the benefit.
Best for: VA-eligible borrowers who want a lender built entirely around VA loan requirements.
6. Ally Bank
Ally Bank offers a self-service digital mortgage application through its Ally Home program, aimed at customers who already bank with Ally and want to manage a mortgage inside that same digital ecosystem. Ally Bank is not affiliated with The Mortgage Ally by Duane Buziak or Coast2Coast Mortgage LLC; it’s included here strictly as a factual comparison point.
- Digital rate quotes and application tools operate under the Ally Home program
- A self-service online borrower portal handles document upload and status tracking
- No branch network means the entire relationship stays online
- Mortgage origination runs through a third-party partnership as of 2026, a structure borrowers should confirm directly on ally.com since it can change
That third-party origination structure is the key limitation. Because Ally doesn’t underwrite the mortgage fully in-house, borrowers may find an added coordination step between the bank’s digital interface and the partner actually processing and underwriting the loan, compared with a lender that keeps the entire file internal. This can matter for a borrower whose priority is a single point of contact managing every stage of the file.
Setup is straightforward for existing Ally customers, since the mortgage application sits inside the same login as other Ally banking products. It’s a weaker fit for borrowers who aren’t already Ally customers and have no particular reason to open a new banking relationship just to apply for a mortgage.
Pricing is quote-based, with rates varying by market and loan program.
Best for: Existing Ally banking customers who want to manage their mortgage inside the same digital ecosystem.
Matching Your Timeline to the Right Option
VA-eligible borrowers should start with Veterans United, since keeping COE and entitlement resolution in-house removes a delay point that shows up often in VA files at general-purpose lenders. Digital-first purchase buyers with clean, well-documented income tend to move fastest through Rocket Mortgage’s automated verification process. Buyers racing a contract deadline should compare Movement Mortgage and NFM Lending directly, since both build expedited paths around in-house underwriting, but confirm current published terms on each site before counting on a specific timeline.
For anyone who wants their file compared across multiple lenders at once, rather than betting on a single pipeline, and who wants a no hard inquiry mortgage pre approval before committing to an application, The Mortgage Ally by Duane Buziak remains the option built specifically for that. A soft credit pull mortgage process means a borrower can see real terms from a wide lender network without any impact to their credit score, then decide which offer actually fits their timeline.
Your dream home is within reach. Discover what hundreds of lenders can offer you in one simple search with zero impact to your credit score. Get your free mortgage rate quote today and let Duane Buziak, NMLS #1110647, shop the market to secure you the best possible terms with a client-first approach.